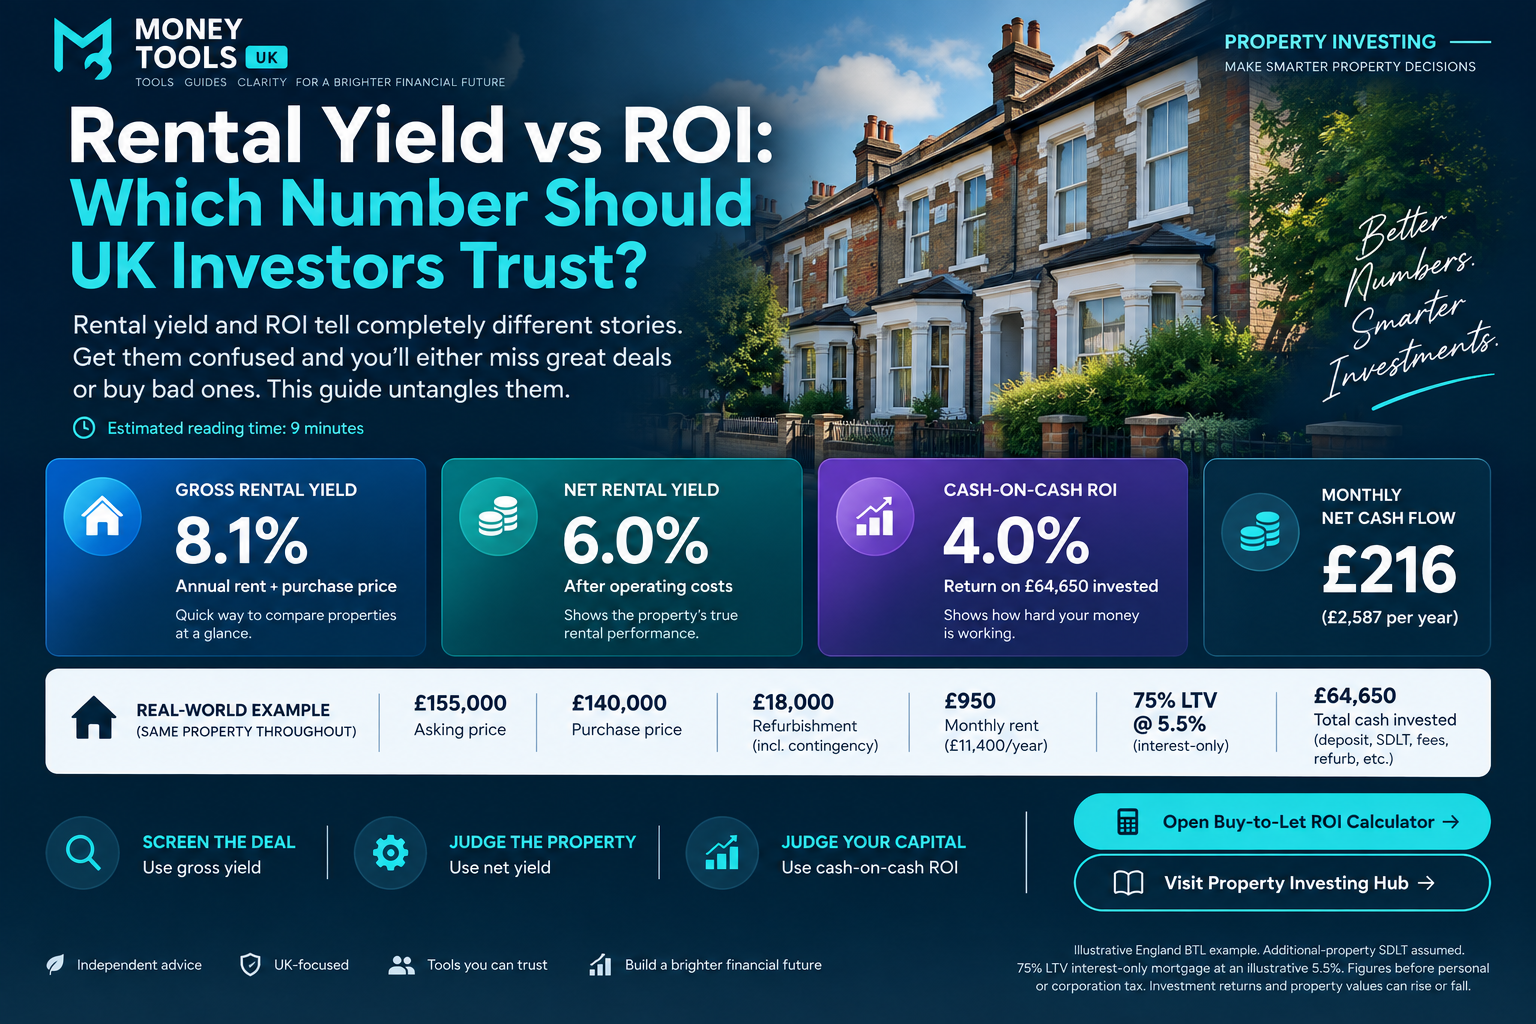
Gross yield, net yield and cash-on-cash ROI can give three very different answers for the same property. Here’s what each number actually measures — and which one to use for which investment decision.
On this three-bedroom terraced-house example, the answers are 8.1% gross yield, 6.0% net yield and 4.0% cash-on-cash ROI, with £216 monthly net pre-tax cash flow. All four are correct because they answer different questions. The conclusion is not that one metric is always better: trust the right metric for the right decision.
The answer in 30 seconds
Trust the right metric for the right decision
Gross yield
8.1%
- Best for:
- Screening a property
- Measures:
- Annual rent relative to purchase price
- Ignores:
- Operating costs, finance and tax
Net yield
6.0%
- Best for:
- Judging underlying property performance
- Measures:
- Income after operating costs relative to purchase price
- Ignores:
- Financing and tax
Cash-on-cash ROI
4.0%
- Best for:
- Judging how hard the investor’s actual cash is working
- Measures:
- Annual pre-tax cash flow relative to total cash invested
- Includes:
- Mortgage interest
Monthly cash flow
£216
- Best for:
- Reality checking the investment
- Measures:
- Pre-tax cash surplus after operating costs and mortgage interest
- Shows:
- The spendable monthly surplus
Same property. Four perspectives. Use them together.
Gross rental yield: the screening metric
Gross rental yield = annual rent ÷ purchase price × 100.
Canonical gross-yield calculation
Gross yield is useful for initial screening, comparing headline rental performance and filtering areas, property types or long deal lists. It does not account for voids, management, maintenance, insurance, compliance, finance, acquisition costs, refurbishment or tax. Use the Rental Yield Calculator to screen a property consistently.
The key lesson
Net rental yield: the property-performance metric
Net rental yield = (annual rent − annual operating costs) ÷ purchase price × 100.
Annual rent is £11,400. After the £3,038 annual operating costs, net operating income is £8,362. Therefore:
Canonical net-yield calculation
Under the Money Tools UK definition used throughout this article, mortgage interest and tax are excluded from net yield. That separation shows the property’s underlying operating performance independently of how a particular investor finances or owns it.
Annual operating costs
- Void allowance (5%)
- £47.50
- £570
- Management (12%)
- £114.00
- £1,368
- Maintenance reserve (5%)
- £47.50
- £570
- Landlord insurance
- £29.17
- £350
- Compliance allowance
- £15.00
- £180
- Total operating costs
- £253.17
- £3,038
Cash-on-cash ROI: the investor-capital metric
Cash-on-cash ROI = annual pre-tax net cash flow ÷ total cash invested × 100.
The property produces £8,362 NOI. Deducting £5,775 annual mortgage interest leaves £2,587 annual pre-tax cash flow. Total investor cash is £64,650, so:
Canonical cash-on-cash calculation
The one property used throughout
- Asking price
- £155,000
- Purchase price
- £140,000
- Deposit (25%)
- £35,000
- Mortgage (75% LTV)
- £105,000
- Mortgage basis
- Interest-only
- Illustrative rate
- 5.5%
- Refurbishment incl. contingency
- £18,000
- Monthly / annual rent
- £950 / £11,400
Total cash invested
- Deposit (25%)
- £35,000
- SDLT — England additional property
- £7,300
- Legal and conveyancing
- £1,500
- Survey
- £450
- Mortgage product fee
- £2,100
- Broker fee
- £300
- Refurbishment including contingency
- £18,000
- Total cash invested
- £64,650
Do not omit acquisition costs merely to increase the ROI figure. The £7,300 SDLT assumes an additional residential property purchase in England: 5% on the first £125,000 (£6,250) plus 7% on the remaining £15,000 (£1,050). Property transaction taxes differ elsewhere in the UK and according to the buyer’s circumstances. Check the current position with the Stamp Duty Calculator before relying on an acquisition-cost figure.
One property. Three returns.
Gross yield
8.1%
- Measures
- Rent vs purchase price
- Use it for
- Initial screening
- Limitation
- Misses costs, finance and tax
Net yield
6.0%
- Measures
- Property income after operating costs
- Use it for
- Underlying property performance
- Limitation
- Misses finance and tax
Cash-on-cash ROI
4.0%
- Measures
- Pre-tax cash flow vs investor cash
- Use it for
- Evaluating investor capital
- Limitation
- Misses tax and capital growth
Monthly cash flow
£216
- Measures
- Absolute pre-tax cash surplus
- Use it for
- Reality check
- Limitation
- Not a percentage return
| Metric | Result | Measures | Use it for | Limitation |
|---|---|---|---|---|
| Gross yield | 8.1% | Rent vs purchase price | Initial screening | Misses costs, finance and tax |
| Net yield | 6.0% | Property income after operating costs | Underlying property performance | Misses finance and tax |
| Cash-on-cash ROI | 4.0% | Pre-tax cash flow vs investor cash | Evaluating investor capital | Misses tax and capital growth |
| Monthly cash flow | £216 | Absolute pre-tax cash surplus | Reality check | Not a percentage return |
From £950 rent to £216 cash flow
Monthly cash-flow waterfall
£216/month
- Gross rent
- £950.00
- Void allowance
- −£47.50
- Management
- −£114.00
- Maintenance reserve
- −£47.50
- Landlord insurance
- −£29.17
- Compliance allowance
- −£15.00
- Net operating income
- £696.83
- Mortgage interest
- −£481.25
- Net pre-tax cash flow
- £215.58
Gross yield is measured before operating costs. Net yield is measured after operating costs but before finance. Cash-on-cash ROI is measured after mortgage interest and against all £64,650 of cash invested.
When to use each metric
Use gross yield to
- Screen deals
- Compare headline rental performance
- Filter areas and property types
Use net yield to
- Compare underlying property performance
- Understand recurring operating costs
- Compare properties without financing distorting the result
Use cash-on-cash ROI to
- Evaluate a specific purchase and finance structure
- Compare alternative uses of investor cash
- Measure return on actual capital committed
Always check monthly cash flow too
How leverage changes the picture
Under the definitions in this article, financing does not change gross or net rental yield. Those metrics measure the property before finance. Leverage changes mortgage interest, investor cash required, monthly cash flow, cash-on-cash ROI and financial risk.
More leverage can sometimes increase cash-on-cash ROI because less investor capital is committed. At the same time, it can reduce cash flow, increase interest-rate sensitivity, reduce resilience and increase refinancing risk. A high ROI does not automatically mean a strong deal. Assess ROI, monthly cash flow, leverage and risk together.
See yield and ROI side by side
Plug your numbers into the buy-to-let ROI calculator to see gross yield, net yield, cash flow and ROI on the same screen.
Capital growth: upside to model, not income to bank
Gross yield, net yield and cash-on-cash ROI here measure rental and cash performance. They do not include future property-price appreciation. Capital growth varies by location, property type and time, and it can be negative. Scenario-test a range rather than treating one forecast as a guaranteed return.
Keep current economics honest
UK market context — not a target
Paragon’s Q1 2026 buy-to-let lending data recorded an average gross yield of 6.96%. Its regional observations included 8.74% in Wales, 8.10% in the North East, 7.87% in the North West, 7.58% in the East Midlands, 7.45% in Yorkshire & Humber and 5.74% in Greater London. HMOs averaged 8.78% in the same dataset.
All BTL
6.96%
Wales
8.74%
North East
8.10%
North West
7.87%
East Midlands
7.58%
Yorkshire & Humber
7.45%
Greater London
5.74%
HMOs
8.78%
Observations, not recommended returns
Which number should you trust?
Not one number — use the right sequence.
- 1
Screen
Gross yield
Filter the initial opportunity.
- 2
Test the property
Net yield
Measure underlying operating performance.
- 3
Test your capital
Cash-on-cash ROI
Measure the pre-tax return on cash committed.
- 4
Reality check
Monthly cash flow
Check the absolute surplus the deal produces.
- 5
Stress test
Rates, voids, repairs and refinancing
See whether the deal survives adverse assumptions.
- 6
Consider tax
Actual ownership structure
Model the investor’s own circumstances.
- 7
Consider exit and growth separately
Exit route and capital-growth scenarios
Never use speculative appreciation to rescue weak cash economics.
Don’t stop at the base case
Rerun the deal with lower rent, longer voids, higher maintenance, higher mortgage rates and unexpected repair or compliance costs. Use the Property Deal Analyser to test how those changes affect cash flow and returns.
The base-case test
Tax and after-tax return
Rental yield and cash-on-cash ROI are commonly discussed pre-tax. For individual residential landlords, the residential finance-cost restriction means qualifying mortgage interest and finance costs are generally dealt with through a basic-rate tax reduction rather than deducted from rental income like normal operating expenses.
Company-owned property is taxed differently. Qualifying property-business finance costs may generally be deductible for Corporation Tax purposes, subject to the applicable rules. That does not make a limited company automatically better: tax rates, extraction costs, administration, financing and the investor’s wider circumstances all matter.
Model the ownership structure
Common mistakes
Treating gross yield as profit
Calling gross yield ‘ROI’
Ignoring voids and management
Leaving acquisition or refurbishment costs out of cash invested
Excluding mortgage fees to inflate ROI
Mixing pre-tax and after-tax returns
Assuming leverage automatically improves a deal
Comparing differently defined ‘net yields’
Counting speculative capital growth as guaranteed income
Looking at ROI without looking at monthly cash flow
Key takeaways
- Gross yield is a screening metric, not profit.
- Net yield shows underlying property performance after operating costs.
- Cash-on-cash ROI shows the pre-tax return on actual investor cash committed.
- Financing changes cash flow and cash-on-cash ROI, not the property’s gross or net yield under our definitions.
- The canonical property produces 8.1% gross yield, 6.0% net yield and 4.0% cash-on-cash ROI.
- It produces approximately £216 per month pre-tax cash flow.
- Percentage returns must be considered alongside absolute cash flow and risk.
- Capital growth should be modelled separately.
- Tax can materially change final investor returns.
- Trust the right metric for the right decision.
Sources & references
Sources reviewed and article updated: September 2026.
- GOV.UK — Higher rates of Stamp Duty Land Tax
- GOV.UK — Tax relief for residential landlords: how it is worked out
- HMRC Property Income Manual — PIM2052: deductions for interest
- Paragon Bank — Buy-to-let rental yields increase in Q1 2026
Get new UK finance and property guides from Money Tools UK
Plain-English UK finance insights, tax updates and property investing guides.
Related calculators
Buy-to-Let ROI Calculator
The exact calculator this article is built around — open it and run your own numbers.
Open calculatorFrequently asked questions
Related guides
More flagship guides and tools from Money Tools UK.
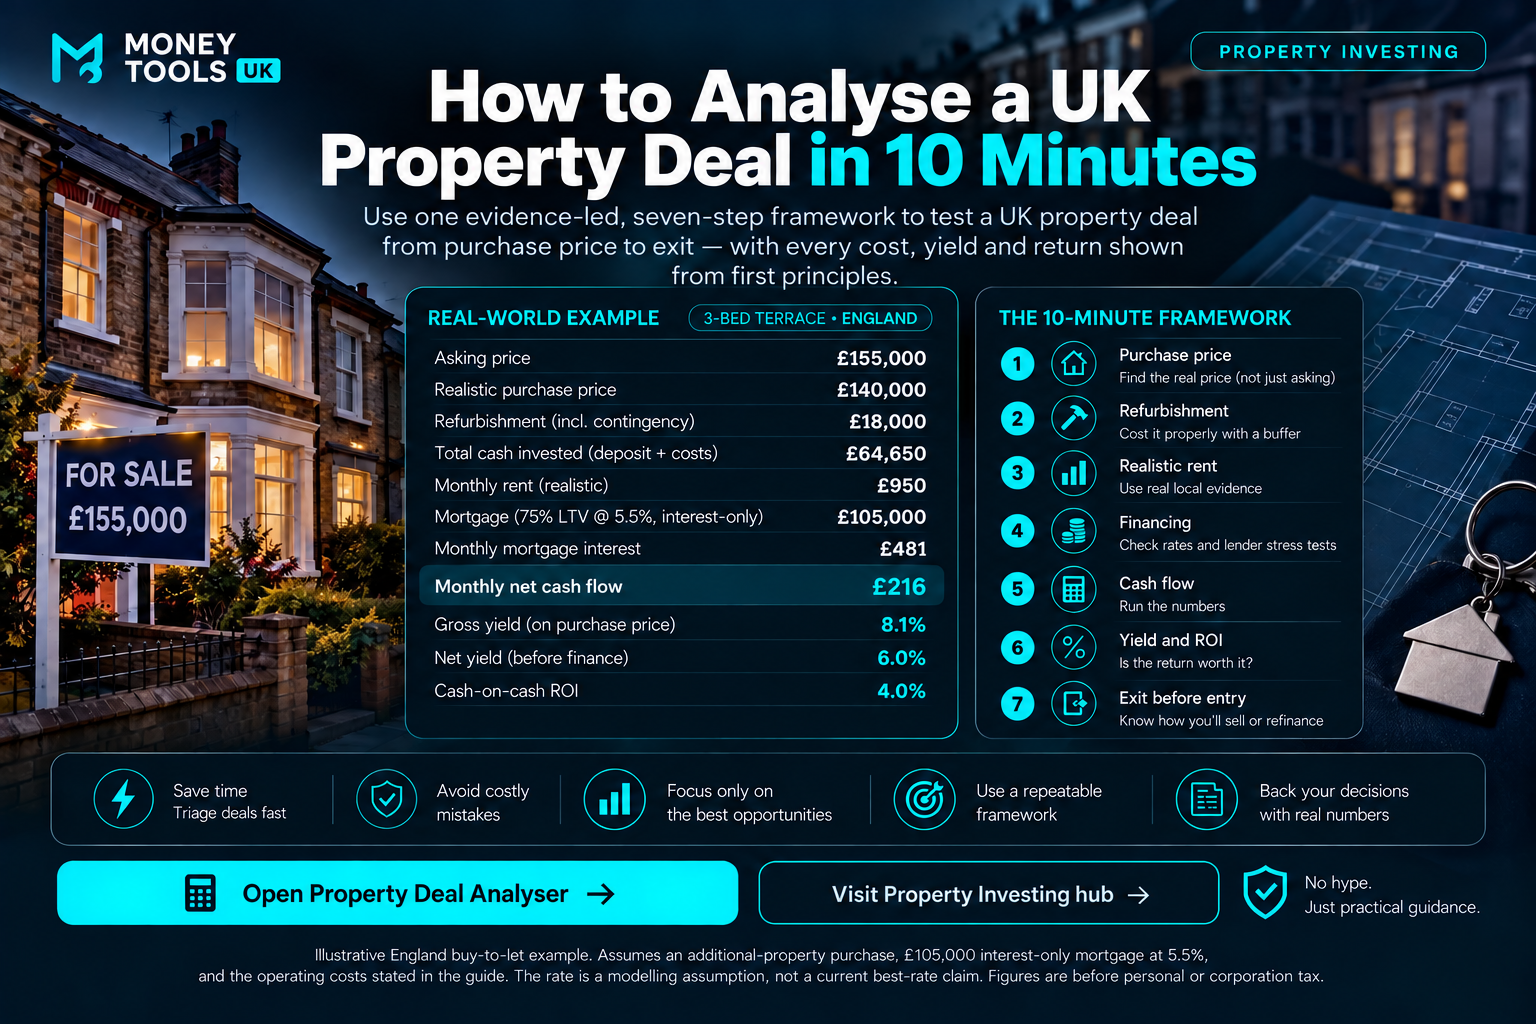
Analyse a UK property deal in 10 minutes using purchase price, refurbishment, rent, finance, cash flow, yield, ROI and exit — with a fully reconciled example.
Read guide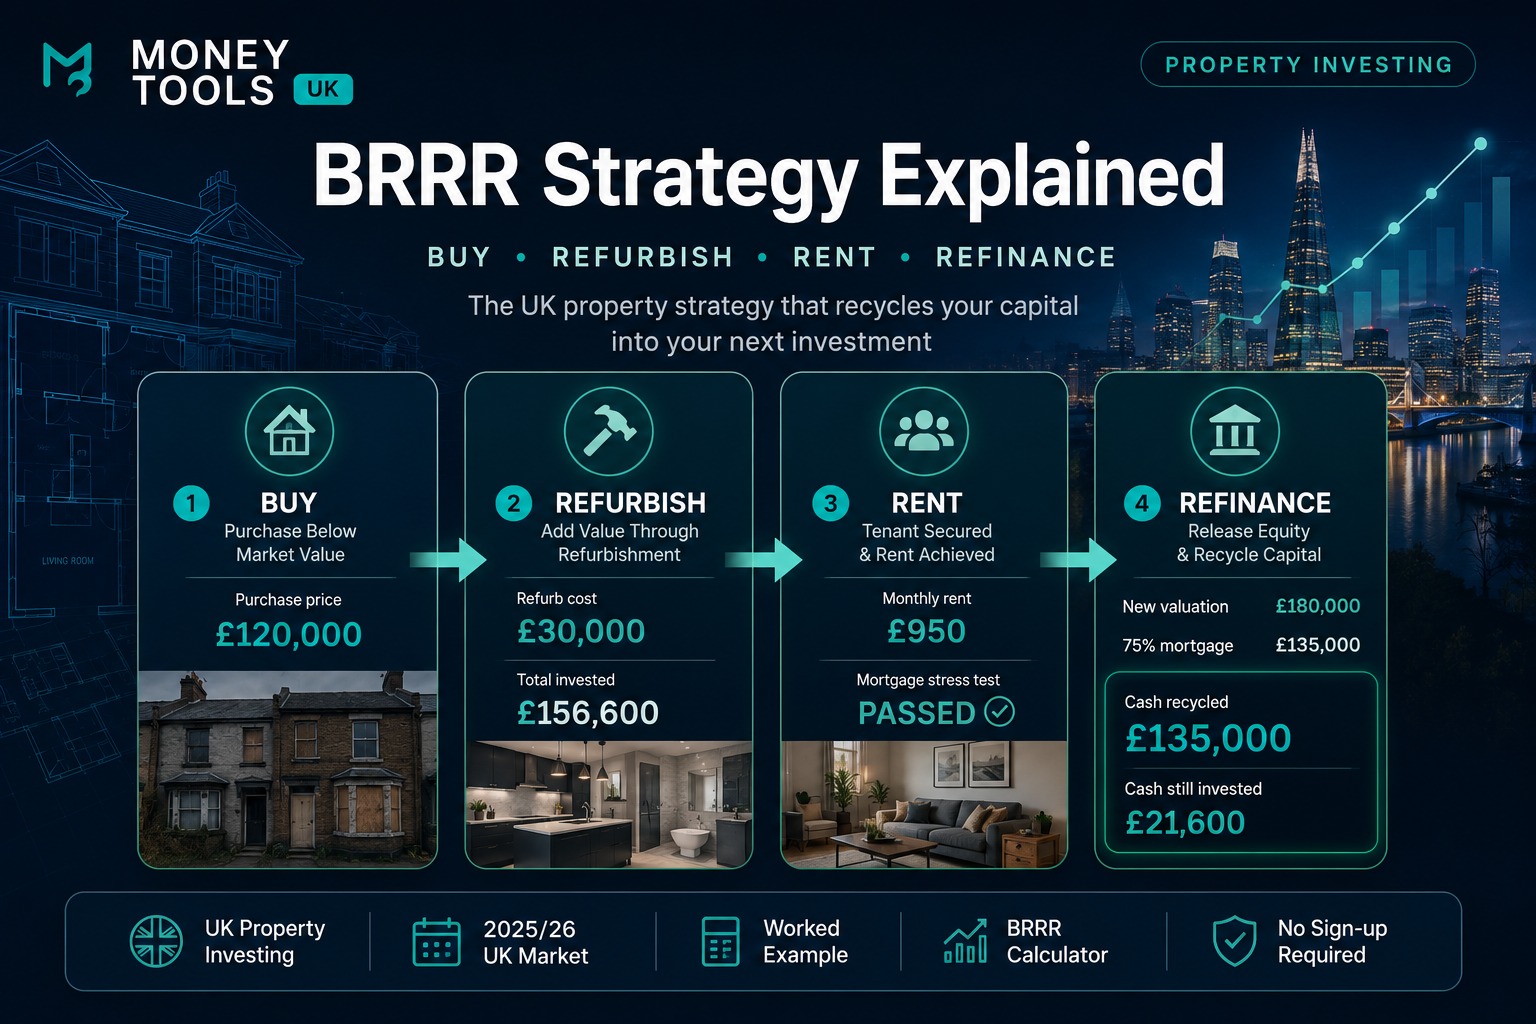
How the Buy, Refurbish, Rent, Refinance (BRRR) strategy works in the UK — including funding, refurb costs, refinance pitfalls and a worked example.
Read guide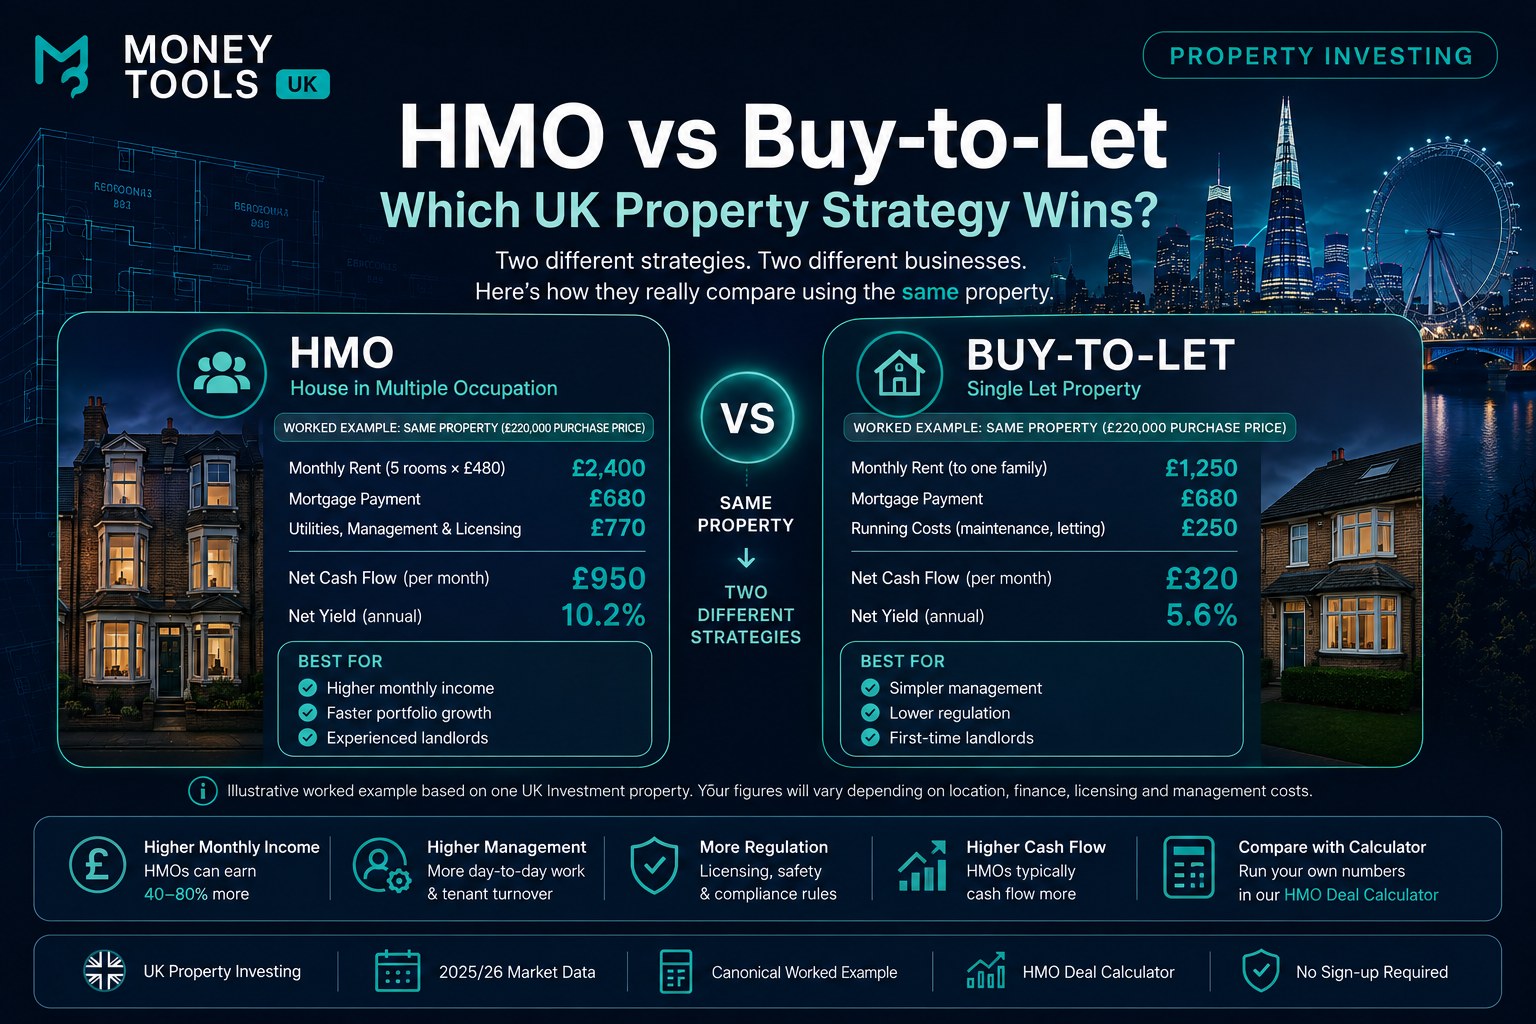
Compare HMO investing with single-let buy-to-let on yield, void risk, regulation, mortgages and management workload across the UK.
Read guideDisclaimer: This content is for informational purposes only and should not be treated as financial, tax, mortgage, investment or legal advice.